What Is Net Worth? Simple Definition, Formula & Examples
If you want to understand your overall financial position, one of the simplest numbers to track is your net worth. In its simplest form, net worth tells you what you own after subtracting everything you owe.
Net worth simple definition :
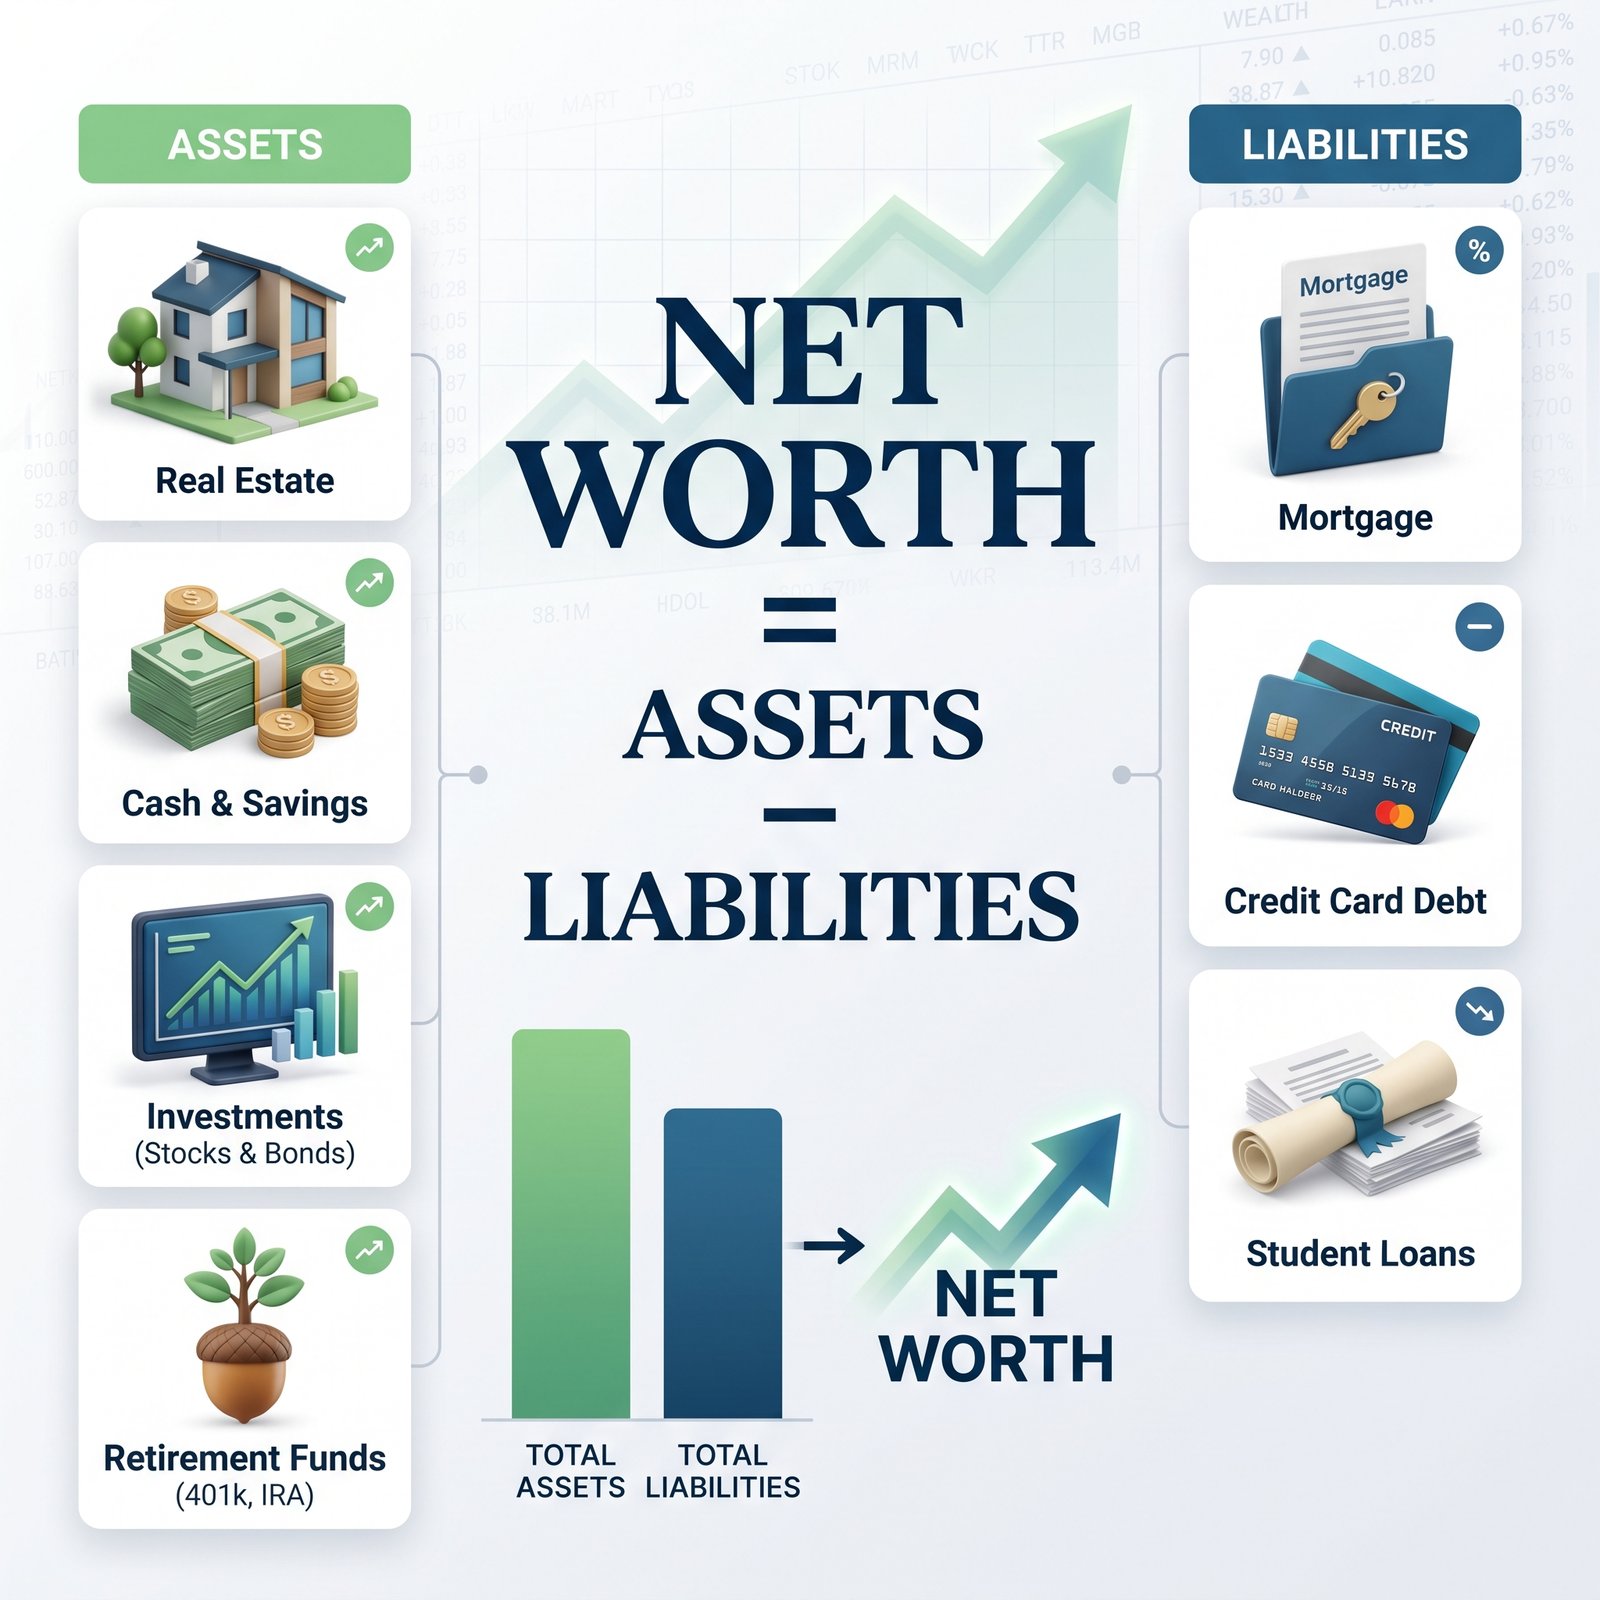
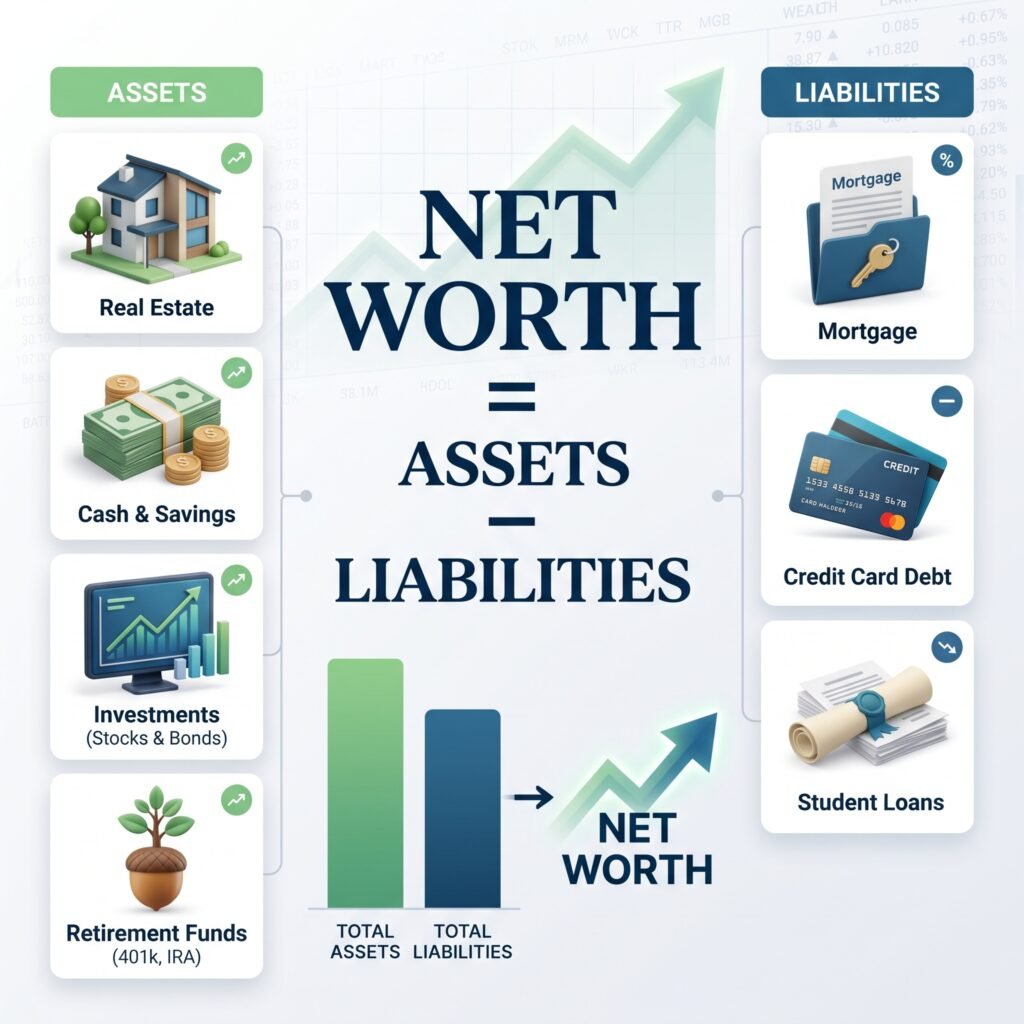
Net Worth = Total Assets − Total Liabilities
For example, if you own $500,000 worth of assets and owe $200,000 in debts, your net worth is $300,000.
Unlike income, which measures how much money you earn over a period of time, net worth provides a snapshot of your accumulated financial position. Someone can have a high income but relatively little net worth if they also have significant debt or spend most of what they earn.
Understanding your net worth can help you monitor financial progress, identify debt problems, and make better long-term financial plans.
What Is Net Worth? Simple Definition
The simplest definition of net worth is the total value of everything you own minus the total amount you owe.
The things you own are called assets, while the money you owe is called liabilities.
So the basic net worth formula is:
Net Worth = Assets − Liabilities
Consider a fictional person who has:
- $500,000 in assets
- $200,000 in liabilities
The calculation is:
$500,000 − $200,000 = $300,000
That person’s net worth is therefore $300,000.
Net worth simple definition : In plain English, if the person sold all of their assets and paid all of their outstanding debts, they would theoretically have $300,000 remaining.
Net worth can be positive, zero, or negative. A positive net worth means assets are worth more than liabilities. A zero net worth means assets and liabilities are equal. A negative net worth means liabilities are greater than assets.
How Is Net Worth Calculated?
Calculating personal net worth is straightforward. You need two main numbers: your total assets and your total liabilities.
Step 1 — Add Up Your Assets
Start by making a list of things that have financial value. Common assets include:
- Cash
- Checking accounts
- Savings accounts
- Stocks
- Bonds
- Mutual funds and other investments
- Retirement accounts
- Real estate
- Vehicles
- Business interests
- Valuable personal property
When estimating your assets, use a reasonable current value rather than automatically using the original purchase price.
For example
Net worth simple definition : if you bought a vehicle several years ago for $30,000 but it is currently worth approximately $15,000, the current value is generally more relevant to a net worth calculation.
Step 2 — Add Up Your Liabilities
Next, list the money you currently owe.
Common liabilities include:
- Mortgage balances
- Credit card debt
- Auto loans
- Student loans
- Personal loans
- Medical debt
- Other outstanding balances
The important figure is generally the amount you still owe, rather than the original amount you borrowed.
Step 3 — Subtract Liabilities From Assets
Once you know your totals, use the formula:
Net Worth = Total Assets − Total Liabilities
For example:
Total assets = $370,000
Total liabilities = $115,000
Therefore:
$370,000 − $115,000 = $255,000
Your net worth would be $255,000.
Net Worth = Assets − Liabilities
The relationship between assets, liabilities, and net worth is at the heart of personal finance.
Generally, increasing valuable assets can increase net worth, while increasing liabilities can decrease it. Paying down debt can also improve your net worth because the amount you owe becomes smaller.
Here is a simple comparison:
| Financial Position | Assets | Liabilities | Net Worth |
|---|---|---|---|
| Person A | $100,000 | $40,000 | $60,000 |
| Person B | $500,000 | $200,000 | $300,000 |
| Person C | $300,000 | $350,000 | -$50,000 |
Person C has a negative net worth because the person’s liabilities are greater than their assets.
This illustrates why looking at assets alone does not tell the complete financial story. A person might own valuable property but also have substantial debt attached to it.
What Counts as an Asset?
An asset is something you own that has measurable financial value.
For personal net worth calculations, common assets include:
Cash and Bank Accounts
Money held in checking and savings accounts generally counts toward net worth.
Investments
Stocks, bonds, mutual funds, and other investments can be included using their current value.
Retirement Accounts
Accounts such as a 401(k) and other retirement savings can generally be included in total net worth.
Real Estate
A home, rental property, land, or another property can be included based on its reasonable current value.
Vehicles
Cars, trucks, motorcycles, and other vehicles can count as assets. However, their current market value should be considered rather than what you originally paid.
Business Ownership
If you own part or all of a business, that ownership interest may have financial value and can potentially be included in a net worth calculation.
Valuable Personal Property
Certain valuable possessions may also be included when they have meaningful financial value. However, everyday household items generally do not need to be individually listed unless they are significant assets.
What Counts as a Liability?
A liability is a financial obligation or debt that you owe to another person, company, or institution.
Common liabilities include mortgages, credit cards, auto loans, student loans, and personal loans.
For example, if your home is worth $400,000 but you still owe $250,000 on the mortgage, the property contributes value to your net worth, but the mortgage is a liability that reduces it.
The same principle applies to vehicles. If a vehicle is worth $20,000 and you owe $8,000 on an auto loan, the $20,000 is an asset while the $8,000 loan balance is a liability.
Understanding both sides of the net worth assets and liabilities equation is important because focusing only on what you own can give you an incomplete picture.
Why Is Net Worth Important?
Many people focus heavily on their salary or monthly income. Income is certainly important, but it does not tell you everything about your financial position.
So, why is net worth important?
Net worth gives you a broader picture of your accumulated financial resources after accounting for debt.
It Shows Your Overall Financial Position
Income tells you how much money comes in, but net worth shows the relationship between what you own and what you owe.
Someone earning a large salary may have substantial debts and limited savings. Another person with a more moderate income may have accumulated significant savings and investments over many years.
Net worth helps put those factors into one overall measurement.
It Helps You Track Financial Progress
Calculating your net worth regularly can show whether your financial position is improving or declining.
For example, you might calculate your net worth once a year and discover that it increased because you saved more, invested consistently, or paid down debt.
The number can change for many reasons, including changes in investment values and property prices, so it should be viewed as a financial snapshot rather than a perfect measure of financial health.
It Helps Identify Debt Problems
Large liabilities can significantly reduce net worth.
If your debt continues increasing while your assets remain relatively stable, your net worth may decline. Tracking the number can make this trend easier to recognize.
It Helps With Financial Planning
Your personal net worth can be one useful measurement when setting long-term financial goals.
You can track changes over time while also considering other important measures such as income, expenses, savings, debt payments, and investment goals.
It Provides a Long-Term Wealth Measure
Monthly income and expenses can change frequently. Net worth can provide a broader view of how your financial position develops over several years.
That makes it particularly useful for monitoring long-term wealth-building progress.
What Is a Good Net Worth?
There is no single net worth number that is automatically “good” for everyone.
An appropriate financial position depends on many factors, including:
- Age
- Income
- Debt
- Location
- Family situation
- Career stage
- Savings rate
- Investments
- Financial goals
Someone early in their career may have a relatively low or even negative net worth because of education loans or other debts. Someone later in their career may have accumulated substantial retirement savings and property.
Comparing your net worth with people of the same age or looking at wealth percentiles can provide context, but these comparisons should be treated carefully. Individual circumstances can vary significantly.
A more useful approach may be to monitor your own financial progress and determine whether your assets, savings, and debt are moving in a direction that supports your goals.
Net Worth vs. Income
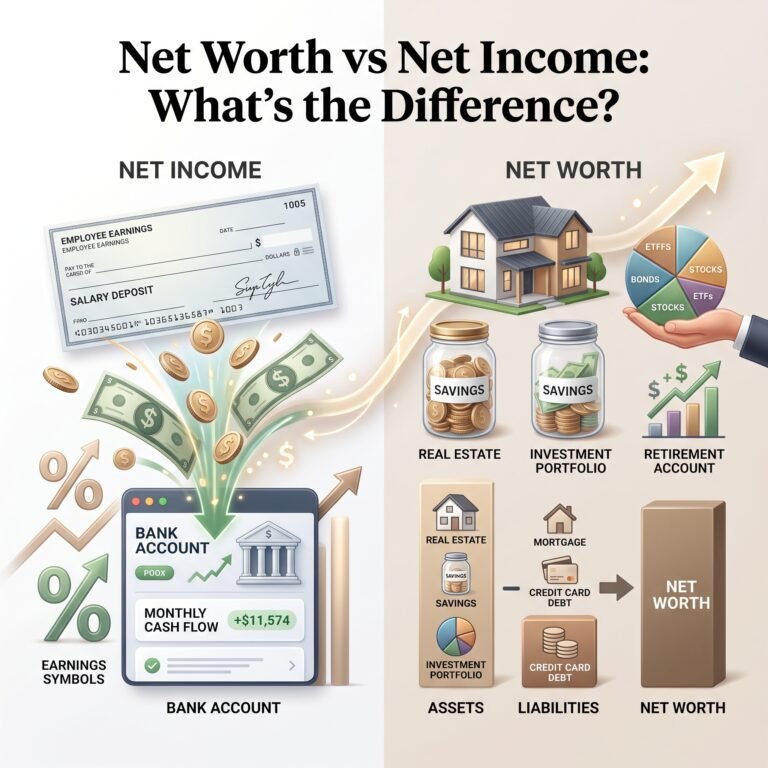
Net worth and income are related, but they measure different things.
Net Worth: What you own minus what you owe.
Income: Money you earn during a specific period.
For example, imagine someone earns $200,000 per year but has significant credit card, mortgage, and personal debt. Their income may be high while their net worth remains relatively modest.
Now imagine another person earns $80,000 per year but has spent many years saving, investing, and paying down debt. They could potentially have substantial accumulated assets.
This does not mean net worth is always more important than income. Income helps you pay expenses, save, invest, and reduce debt, while net worth measures the financial position those activities have helped create.
Does Your Home Count Toward Net Worth?
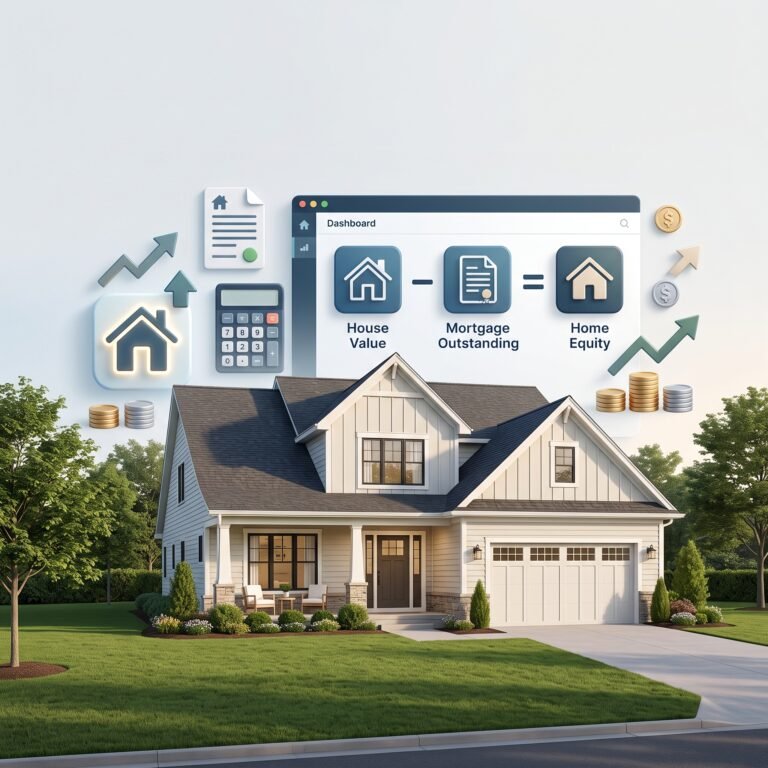
Yes, a home can generally be included when calculating net worth.
The home’s current value is an asset, while the remaining mortgage is a liability.
For example:
- Home value = $400,000
- Mortgage remaining = $250,000
- Home equity = $150,000
The $150,000 of home equity contributes to net worth.
In other words:
$400,000 − $250,000 = $150,000
For a more detailed explanation, a future guide on Does Net Worth Include Your Home? can explore home equity and its role in personal wealth calculations.
Does a 401(k) Count Toward Net Worth?
Generally, yes. A 401(k) and other retirement accounts can be included when calculating total net worth.
For example, if you have $100,000 in a 401(k), that account generally represents an asset when calculating your overall net worth.
However, it is useful to distinguish between total net worth and liquid net worth. Total net worth can include assets such as retirement accounts and real estate, while liquid net worth focuses more heavily on assets that can be converted to cash relatively easily.
A future article on Does a 401(k) Count Toward Net Worth? can provide a more detailed explanation of retirement accounts and net worth.
What Is a Statement of Net Worth?
A statement of net worth is a financial snapshot that lists your assets, liabilities, and resulting net worth.
The basic structure is:
Assets − Liabilities = Net Worth
For example:
| Category | Amount |
| Total Assets | $370,000 |
| Total Liabilities | $115,000 |
| Net Worth | $255,000 |
A statement of net worth can be useful for personal financial planning and situations where a person’s overall financial position needs to be documented.
It provides a simple way to organize financial information in one place.
How to Calculate Your Own Net Worth
You can calculate your personal net worth with a simple process.
Step 1: List All Assets
Write down your cash, bank accounts, investments, retirement accounts, real estate, vehicles, business interests, and other meaningful assets.
Step 2: Estimate Current Values
Use reasonable current values for your assets rather than automatically relying on original purchase prices.
Step 3: List All Liabilities
Include mortgages, credit cards, auto loans, student loans, personal loans, and other outstanding debts.
Step 4: Calculate Total Assets
Add the current values of all your assets.
Step 5: Calculate Total Liabilities
Add the outstanding balances of all your debts.
Step 6: Subtract Liabilities From Assets
Use:
Net Worth = Total Assets − Total Liabilities
For example, if your assets total $250,000 and your liabilities total $100,000:
$250,000 − $100,000 = $150,000
Your estimated net worth is $150,000.
Net Worth Example
Consider a fictional person with the following assets:
- Savings: $25,000
- Investments: $75,000
- Retirement: $100,000
- Home equity: $150,000
- Vehicle: $20,000
Total assets = $370,000
Now consider the liabilities:
- Mortgage: $100,000
- Auto loan: $10,000
- Credit card debt: $5,000
Total liabilities = $115,000
The net worth calculation is:
$370,000 − $115,000 = $255,000
Therefore, the fictional person’s net worth is $255,000.
This example demonstrates the basic relationship between assets and liabilities. The goal is not simply to accumulate assets but to understand the value that remains after outstanding obligations are considered.
How to Increase Your Net Worth
If your goal is to build wealth over time, several general financial habits can help improve your net worth.
Increase Savings
Saving more money can increase your cash and investment assets over time.
Pay Down High-Interest Debt
Reducing outstanding high-interest debt can improve your financial position because liabilities are a direct component of the net worth formula.
Build Investments Over Time
Investing can help build assets over the long term, although investments involve risk and returns are not guaranteed.
Contribute to Retirement Accounts
Regular retirement contributions can help build long-term assets.
Avoid Unnecessary Debt
Taking on debt should be considered carefully because additional liabilities can reduce net worth.
Increase Income Where Possible
Higher income can create more opportunities to save, invest, and pay down debt, although income itself does not automatically increase net worth.
Build Valuable Assets
Building savings, investments, business interests, or other assets can contribute to long-term financial growth.
Review Your Finances Regularly
Calculating your net worth periodically can help you see whether your overall financial position is moving in the direction you want.
These are general educational principles rather than individualized financial advice. Investment decisions should account for your own circumstances, goals, risk tolerance, and financial situation.
8. FAQ
What is net worth in simple terms?
Net worth is what you own minus what you owe. Your assets are added together, your liabilities are added together, and the liabilities are subtracted from the assets.
What is the formula for net worth?
The standard formula is:
Net Worth = Total Assets − Total Liabilities
Is net worth assets minus liabilities?
Yes. Net worth is calculated by subtracting total liabilities from total assets.
Why is knowing your net worth important?
Knowing your net worth can help you understand your overall financial position, track progress over time, identify debt problems, and support long-term financial planning.
Does a house count toward net worth?
Generally, yes. The current value of the home is an asset, while the remaining mortgage is a liability. The difference represents home equity.
Does a 401(k) count toward net worth?
Generally, yes. A 401(k) is a financial asset and can typically be included when calculating total net worth.
Can net worth be negative?
Yes. Net worth can be negative when total liabilities are greater than total assets. For example, $100,000 in assets and $150,000 in liabilities would produce a net worth of -$50,000.
9. Conclusion
The net worth simple definition is easy to remember: what you own minus what you owe.
The formula is:
Net Worth = Total Assets − Total Liabilities
Assets can include cash, investments, retirement accounts, real estate, vehicles, and business interests. Liabilities can include mortgages, credit cards, auto loans, student loans, and other outstanding debts.
Understanding your net worth gives you a broader view of your financial position than income alone. By calculating it periodically, you can track changes in your wealth, recognize debt-related challenges, and measure long-term financial progress.
There is no universal net worth number that everyone should have. What matters is understanding your own financial position and using that information to make informed decisions about saving, debt, investing, and long-term goals.
Once you understand the basics of assets, liabilities, and net worth, you have a strong foundation for exploring more advanced personal finance topics.