Net Worth vs Net Income: What’s the Difference?
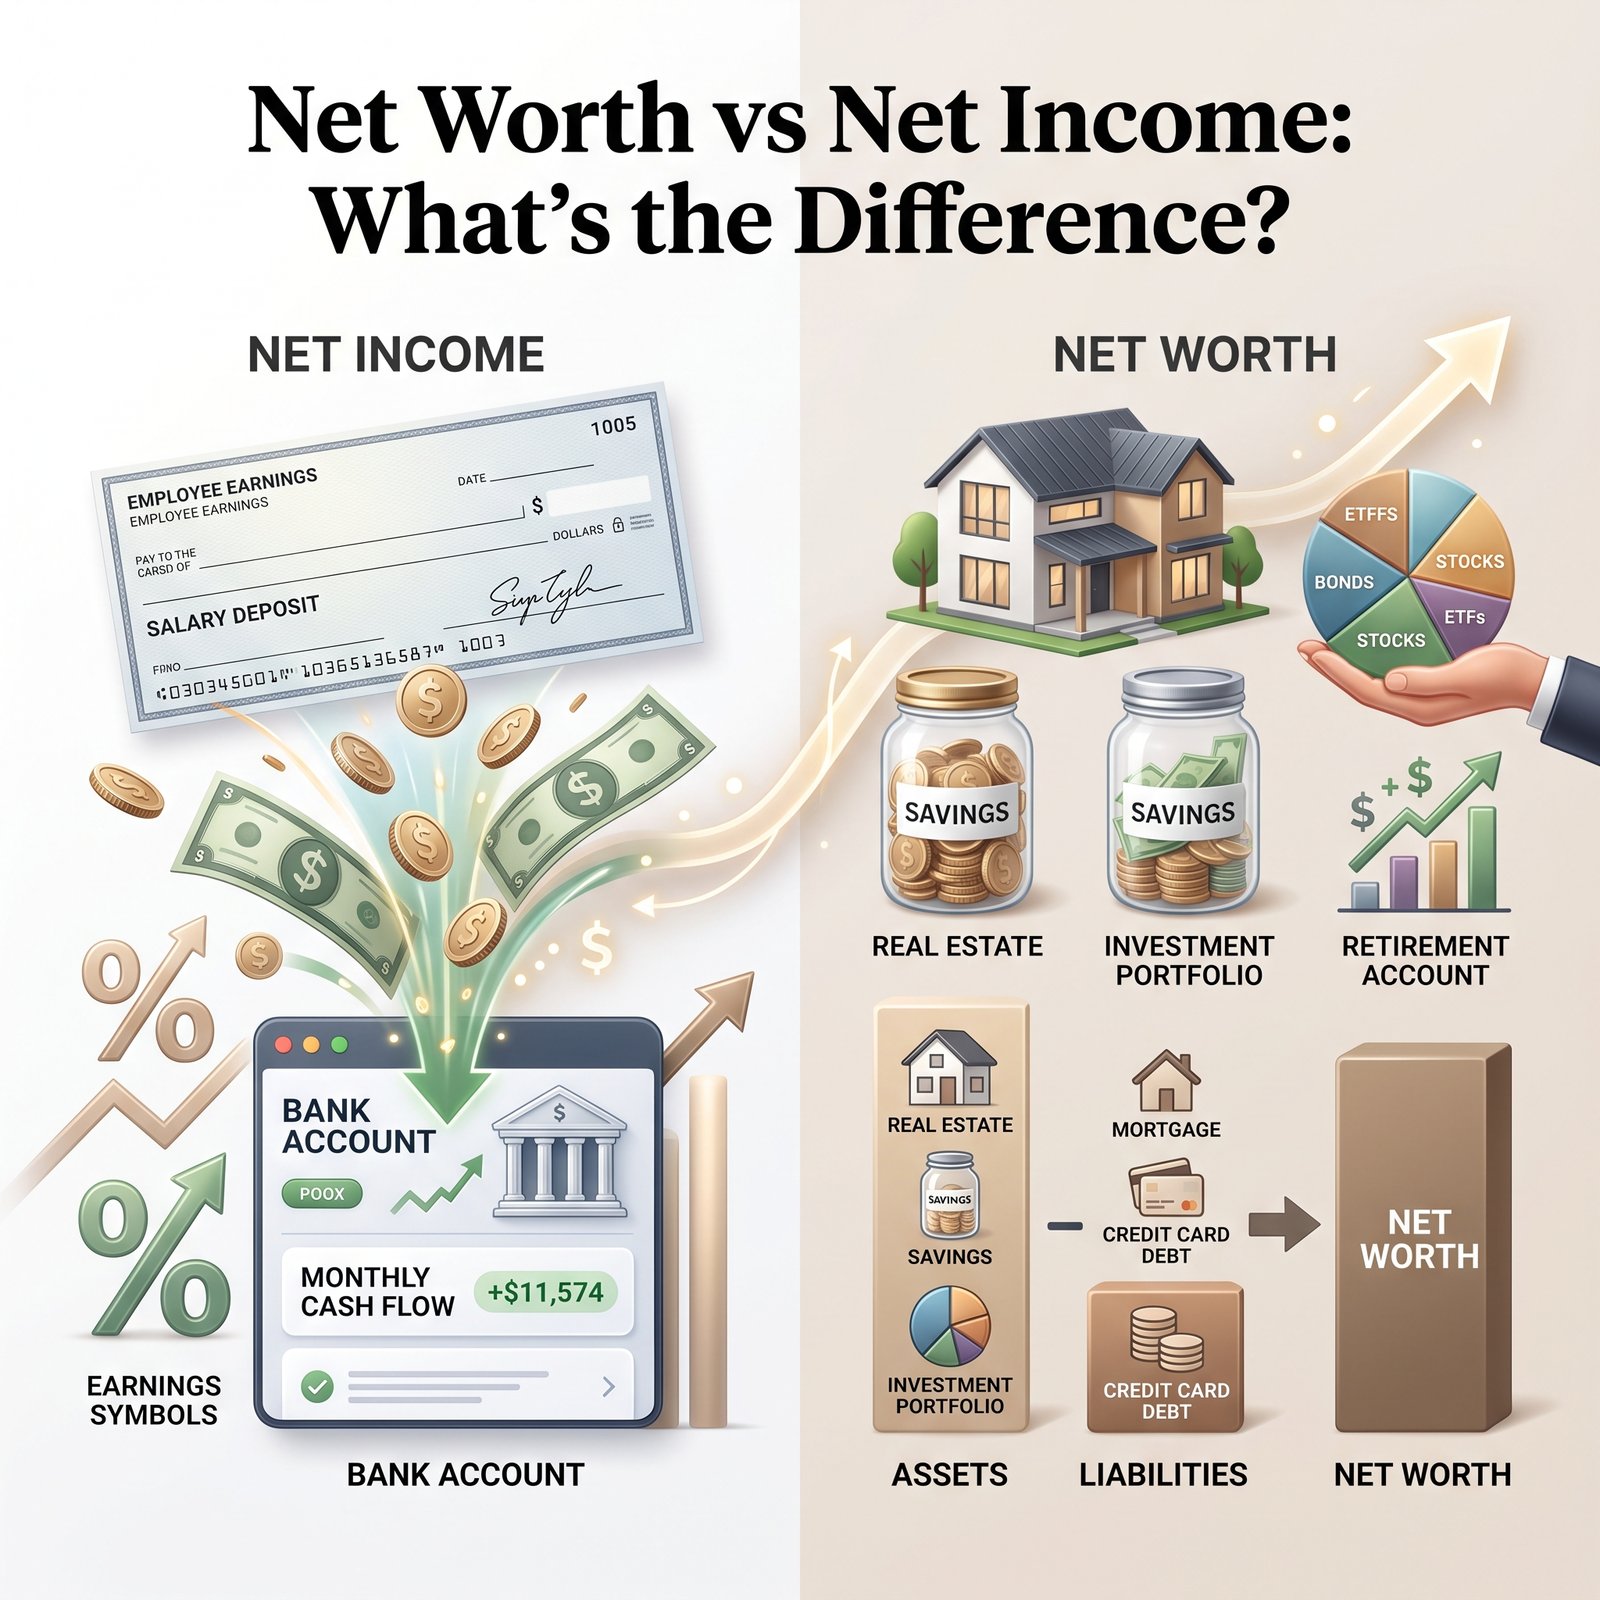
Net worth vs net income is an important distinction in personal finance. Although both numbers tell you something about your financial situation, they measure completely different things. Net income generally tells you how much money you receive after applicable taxes and deductions over a period of time, while net worth shows the value of what you own after subtracting what you owe.
In simple terms, income measures your earnings, while net worth measures your accumulated financial position.
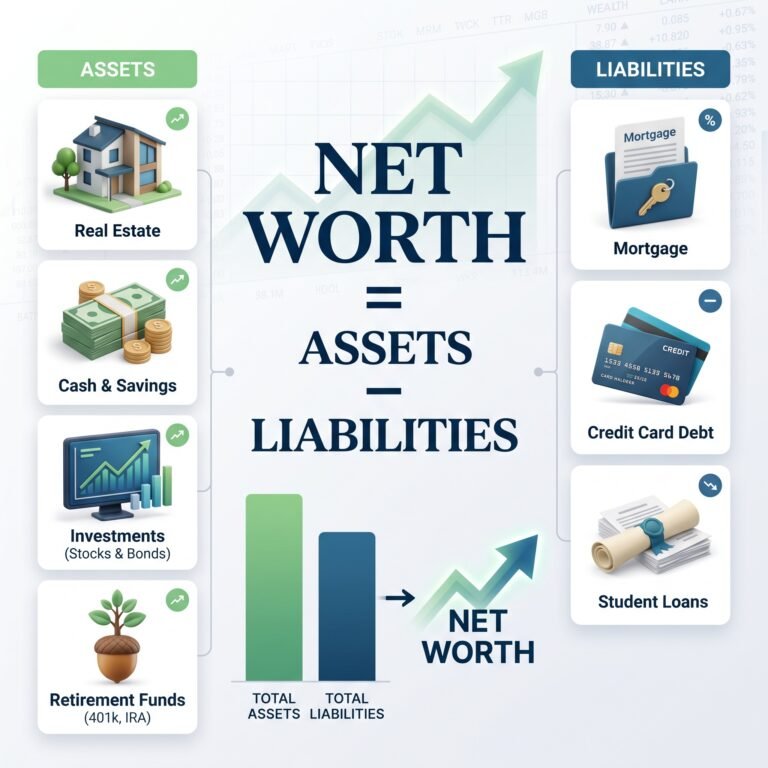
The basic formula for net worth is:
Net Worth = Total Assets − Total Liabilities
For example, if you own $500,000 in assets and have $200,000 in debts, your net worth is $300,000. Understanding both numbers can help you see not only how much you earn, but also whether you are building wealth over time.
What Is Net Worth?
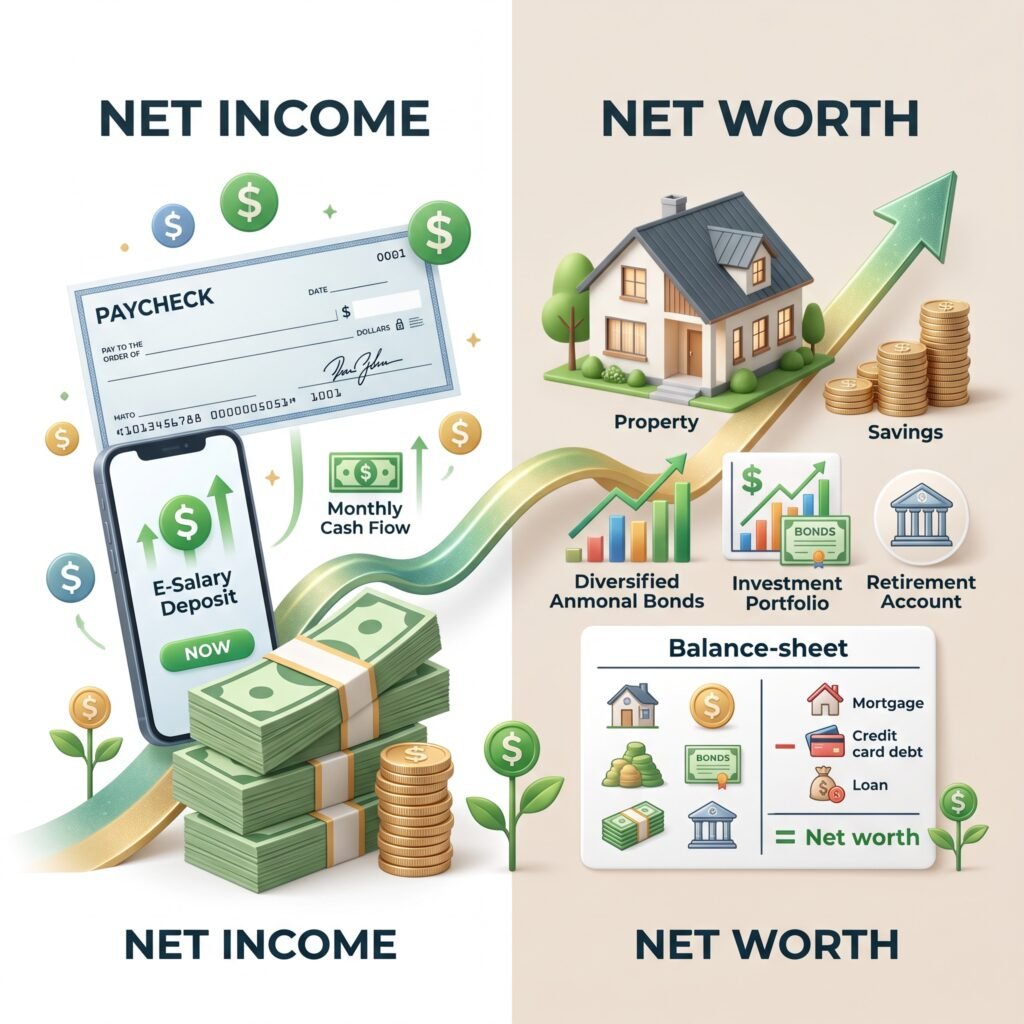
Net worth is the value of your assets after subtracting your liabilities. It provides a snapshot of your financial position at a particular point in time.
Net Worth Formula
Net Worth = Total Assets − Total Liabilities
Your assets may include:
- Cash
- Savings accounts
- Investments
- Retirement accounts
- Real estate
- Vehicles
- Other valuable personal assets
Your liabilities may include:
- Mortgage debt
- Credit card balances
- Student loans
- Auto loans
- Personal loans
- Other outstanding debts
Simple Example
Suppose you have:
Total Assets = $500,000
Total Liabilities = $200,000
Your net worth would be:
$500,000 − $200,000 = $300,000
So, your net worth is $300,000.
Net worth can increase when your assets grow, your debts decrease, or both happen at the same time.
What Is Net Income?
Net income is generally the amount of income remaining after applicable taxes and other deductions. For an employee, it is often closely related to the amount received in their paycheck.
It is important to distinguish gross income from net income.
- Gross income: Your income before applicable taxes and deductions.
- Net income: Your income after applicable taxes and deductions.
For example, imagine an employee earns a gross salary of $80,000 per year. After taxes and other applicable payroll deductions, they might receive $62,000 during the year.
That $62,000 is an example of net income, but the exact amount depends on the individual’s circumstances.
Net income is measured over a period, such as a month or year. Net worth, by contrast, is generally measured at a specific point in time.
Net Worth vs Net Income: Key Difference
The easiest way to understand net worth vs net income is to remember:
Net income is what you earn. Net worth is what you have accumulated after accounting for what you owe.
| Feature | Net Worth | Net Income |
|---|---|---|
| Measures | Wealth/financial position | Earnings after applicable deductions |
| Type | Financial snapshot | Income over a period |
| Main formula | Assets − liabilities | Income − applicable deductions |
| Includes assets? | Yes | No |
| Includes debts? | Yes, as liabilities | Not directly in the same way |
| Measures wealth? | Yes | No |
| Measures earnings? | No | Yes |
These metrics work together, but they should not be treated as interchangeable.
Net Worth vs Net Income Formula
Net Worth Formula
The standard personal finance formula is:
Net Worth = Total Assets − Total Liabilities
For example:
Assets = $750,000
Liabilities = $300,000
Net Worth = $450,000
Net Income Formula
For personal income, a simplified representation is:
Net Income = Gross Income − Taxes − Other Applicable Deductions
The exact calculation can vary based on employment, taxes, benefits, location, and other circumstances.
Business net income is different. In business accounting, net income may involve revenue, operating expenses, taxes, interest, and other accounting items. Therefore, personal net income should not be confused with business net income.
Example of Net Worth vs Net Income
Consider a fictional person with the following financial information:
Annual gross income: $100,000
Net annual income: $76,000
Total assets: $450,000
Total liabilities: $250,000
Their net worth is:
$450,000 − $250,000 = $200,000
Here, the $76,000 net income represents money received after applicable deductions during the year.
The $200,000 net worth represents the person’s financial position based on their assets and liabilities.
This example shows why a person’s annual income and net worth can be completely different numbers.
Can Someone Have a High Income but Low Net Worth?
Yes. A person can earn a high salary and still have a relatively low net worth.
A high income provides greater earning potential, but it does not automatically create wealth. Spending, debt, saving, investing, and other financial decisions also affect net worth.
For example, someone earning $200,000 per year might have:
- Large credit card balances
- A substantial auto loan
- A large mortgage
- High annual spending
- Limited savings
- Few investments
If their liabilities are high and their assets are relatively low, their net worth may remain modest despite their high income.
This does not mean that everyone with a high income manages money poorly. Housing costs, family responsibilities, location, education expenses, and other circumstances can significantly affect someone’s financial position.
Can Someone Have a Low Income but High Net Worth?
Yes, someone with a modest income can have a substantial net worth.
This can happen when a person accumulates assets over many years while keeping debt under control.
For example, a retired person might have relatively low annual income but own:
- A paid-off home
- Retirement investments
- Savings
- Other assets
If those assets are worth significantly more than the person’s liabilities, their net worth can be high even though their current income is relatively modest.
Long-term investing, saving, home equity, business ownership, inheritance, and debt reduction can all contribute to accumulated wealth.
Why Income Does Not Equal Wealth
One of the most important personal finance concepts is that income is not the same as wealth.
Income is money you receive during a period. Net worth reflects the assets you have accumulated after accounting for your liabilities.
A simplified wealth-building path can look like this:
Income → Savings → Investments/Assets → Potential Growth → Higher Net Worth
However, this process is not automatic.
Someone can earn a large income but spend nearly all of it. Another person may earn less but consistently save, invest, and reduce debt over many years.
This is why looking only at salary can give an incomplete picture of someone’s financial position.
How Income Can Affect Net Worth
Income can play an important role in building net worth because it can provide money for saving, investing, and debt repayment.
For example, a person may use part of their income to:
- Build an emergency fund
- Pay down debt
- Invest for retirement
- Purchase assets
- Build home equity
- Grow a business
Over time, these actions may contribute to a higher net worth.
However, net worth can also decrease while income stays the same. For example, investment values may fall, property values may decline, or liabilities may increase.
Therefore, income is an important input into wealth building, but it is not a direct measure of wealth.
Which Matters More: Net Worth or Net Income?
Neither metric is universally more important. They answer different financial questions.
Net income helps you understand:
- Your earning power
- Money available after applicable deductions
- Your ability to cover expenses
- Your potential capacity to save
Net worth helps you understand:
- Your accumulated wealth
- Your assets
- Your debt levels
- Your overall financial position
- Your progress toward long-term wealth goals
Someone trying to improve their finances can benefit from monitoring both.
For example, increasing income may provide more opportunities to save and invest, while tracking net worth shows whether those actions are actually improving your overall financial position.
Net Worth vs Net Income for Financial Health
Looking at both metrics together can provide a more complete picture.
High Income + Low Net Worth
This could mean the person has strong earning power but has not accumulated substantial assets relative to liabilities.
Low Income + High Net Worth
This may occur when someone has accumulated investments, property, retirement savings, or other assets over many years.
High Income + High Net Worth
This can indicate strong earning power combined with substantial accumulated assets, although these two numbers alone do not measure every aspect of financial health.
Low Income + Low Net Worth
This does not mean financial improvement is impossible. Tracking progress over time can help someone understand how savings, debt reduction, and asset growth are changing their financial position.
How to Calculate Your Net Worth
Calculating net worth is relatively straightforward.
Step 1: List Your Assets
Include assets such as:
- Bank accounts
- Investments
- Retirement accounts
- Real estate
- Vehicles
- Other valuable assets
Step 2: Estimate Current Values
Use reasonable current values rather than automatically relying on what you originally paid.
Step 3: Add Your Assets
Calculate the total value of everything included in your asset list.
Step 4: List Your Liabilities
Include:
- Mortgage
- Credit cards
- Student loans
- Auto loans
- Personal loans
- Other debts
Step 5: Add Your Liabilities
Calculate the total amount you currently owe.
Step 6: Subtract Liabilities From Assets
Use:
Net Worth = Assets − Liabilities
For example:
Assets = $600,000
Liabilities = $250,000
Net Worth = $350,000
Tracking the same categories consistently can make changes in your net worth easier to understand over time.
How to Calculate Your Net Income
For an employee, a simple approach is:
- Start with gross income.
- Subtract applicable taxes.
- Subtract applicable payroll deductions.
- Determine the amount actually received.
For example:
Gross income = $90,000
After applicable taxes and deductions, suppose the employee receives:
Net income = $68,000
The actual amount will vary based on individual circumstances.
Freelancers and business owners may have more complicated calculations because income, business expenses, taxes, and other factors can be handled differently.
How to Track Net Worth and Net Income
You do not necessarily need complicated software to track these numbers.
Monthly
Consider tracking:
- Income
- Expenses
- Savings
- Debt payments
Quarterly or Annually
Review:
- Net worth
- Investment balances
- Retirement accounts
- Home equity
- Major liabilities
The goal is to understand trends, rather than becoming overly focused on a single number.
For example, if your net income remains relatively stable while your debt decreases and investments increase, your net worth may improve over time.
Common Mistakes People Make
Several mistakes can make it harder to understand the difference between income and wealth.
Confusing Income With Wealth
A large paycheck does not automatically mean a large net worth.
Forgetting Liabilities
Only adding assets will overstate your net worth. Debts must also be included.
Using Gross Income Instead of Net Income
Gross income and net income are different measurements. Be clear about which figure you are tracking.
Treating Home Value as Home Equity
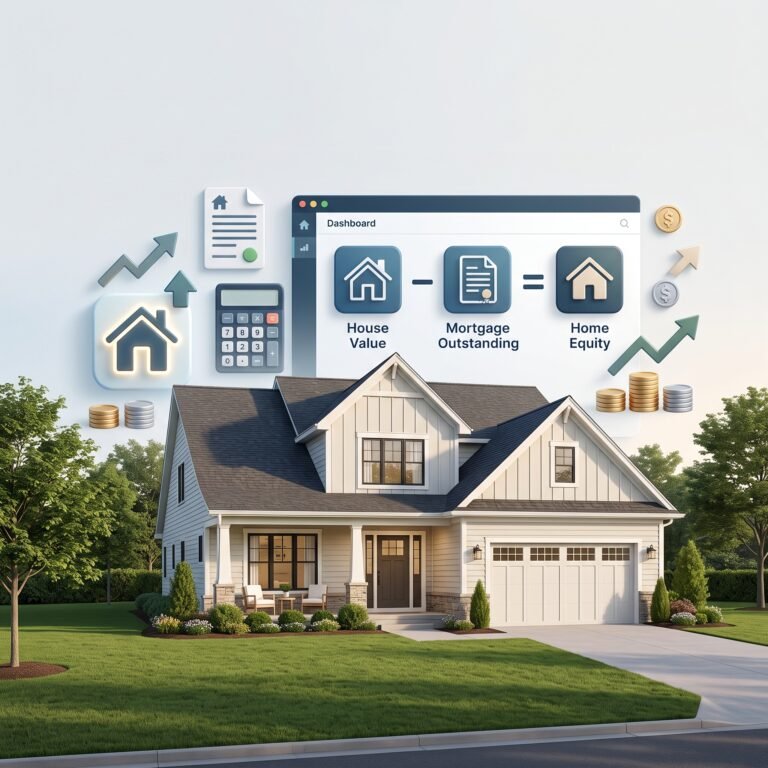
If you own a home with a mortgage, the full property value is not the same as your home equity.
Focusing Only on Salary
Salary is important, but savings, investments, debt, and assets also influence long-term financial position.
Assuming High Income Guarantees Financial Security
Income can change, while assets and liabilities also change. Looking at both income and net worth provides more context.
Frequently Asked Questions
What is the difference between net worth and net income?
Net income measures money received after applicable deductions over a period, while net worth measures assets minus liabilities at a particular point in time.
Is net worth the same as annual income?
No. Annual income measures earnings during a year. Net worth measures your financial position based on assets and liabilities.
Is net income included in net worth?
Income itself is not a separate component of net worth simply because it is earned. However, money saved from income can become an asset and therefore contribute to net worth.
Can you have a high income but low net worth?
Yes. High spending, significant debt, limited savings, or limited investments can result in a relatively low net worth despite high income.
Can you have a low income but high net worth?
Yes. Long-term saving, investing, home ownership, inheritance, business ownership, or accumulated retirement assets can contribute to high net worth.
Which is more important, income or net worth?
Neither is universally more important. Income helps measure earning capacity, while net worth helps measure accumulated wealth and overall financial position.
Does salary affect net worth?
Salary can affect net worth because it provides income that can potentially be saved, invested, or used to reduce debt. However, salary alone does not determine net worth.
How does debt affect net worth?
Debt is generally a liability. Because net worth equals assets minus liabilities, increasing debt can reduce net worth when other factors remain unchanged.
Does savings count toward net worth?
Yes. Money held in savings accounts is generally an asset and can therefore contribute to net worth.
Does home equity count toward net worth?
Generally, yes. Home equity represents the portion of a property’s value that remains after subtracting the outstanding mortgage and other relevant secured debt.
Does a 401(k) count toward net worth?
Generally, yes. A 401(k) is an asset and can be included when calculating total net worth, although its treatment can differ when calculating liquid net worth.
How often should I calculate my net worth?
Many people find quarterly or annual tracking useful. The most important factor is using a consistent method so that changes over time are meaningful.
Conclusion
Understanding net worth vs net income is essential for building a clearer picture of your personal finances. Net income tells you how much you earn after applicable deductions over a period, while net worth tells you the value of your assets after subtracting your liabilities.
A high income does not automatically create wealth, just as a modest income does not prevent someone from building substantial wealth over time. Saving, investing, managing debt, and accumulating assets can all influence net worth.
For a more complete view of your financial health, consider tracking both net income and net worth. Income shows your current earning power, while net worth helps you see how your financial position is developing over time.