Home Equity and Net Worth: A Complete Guide in 2026
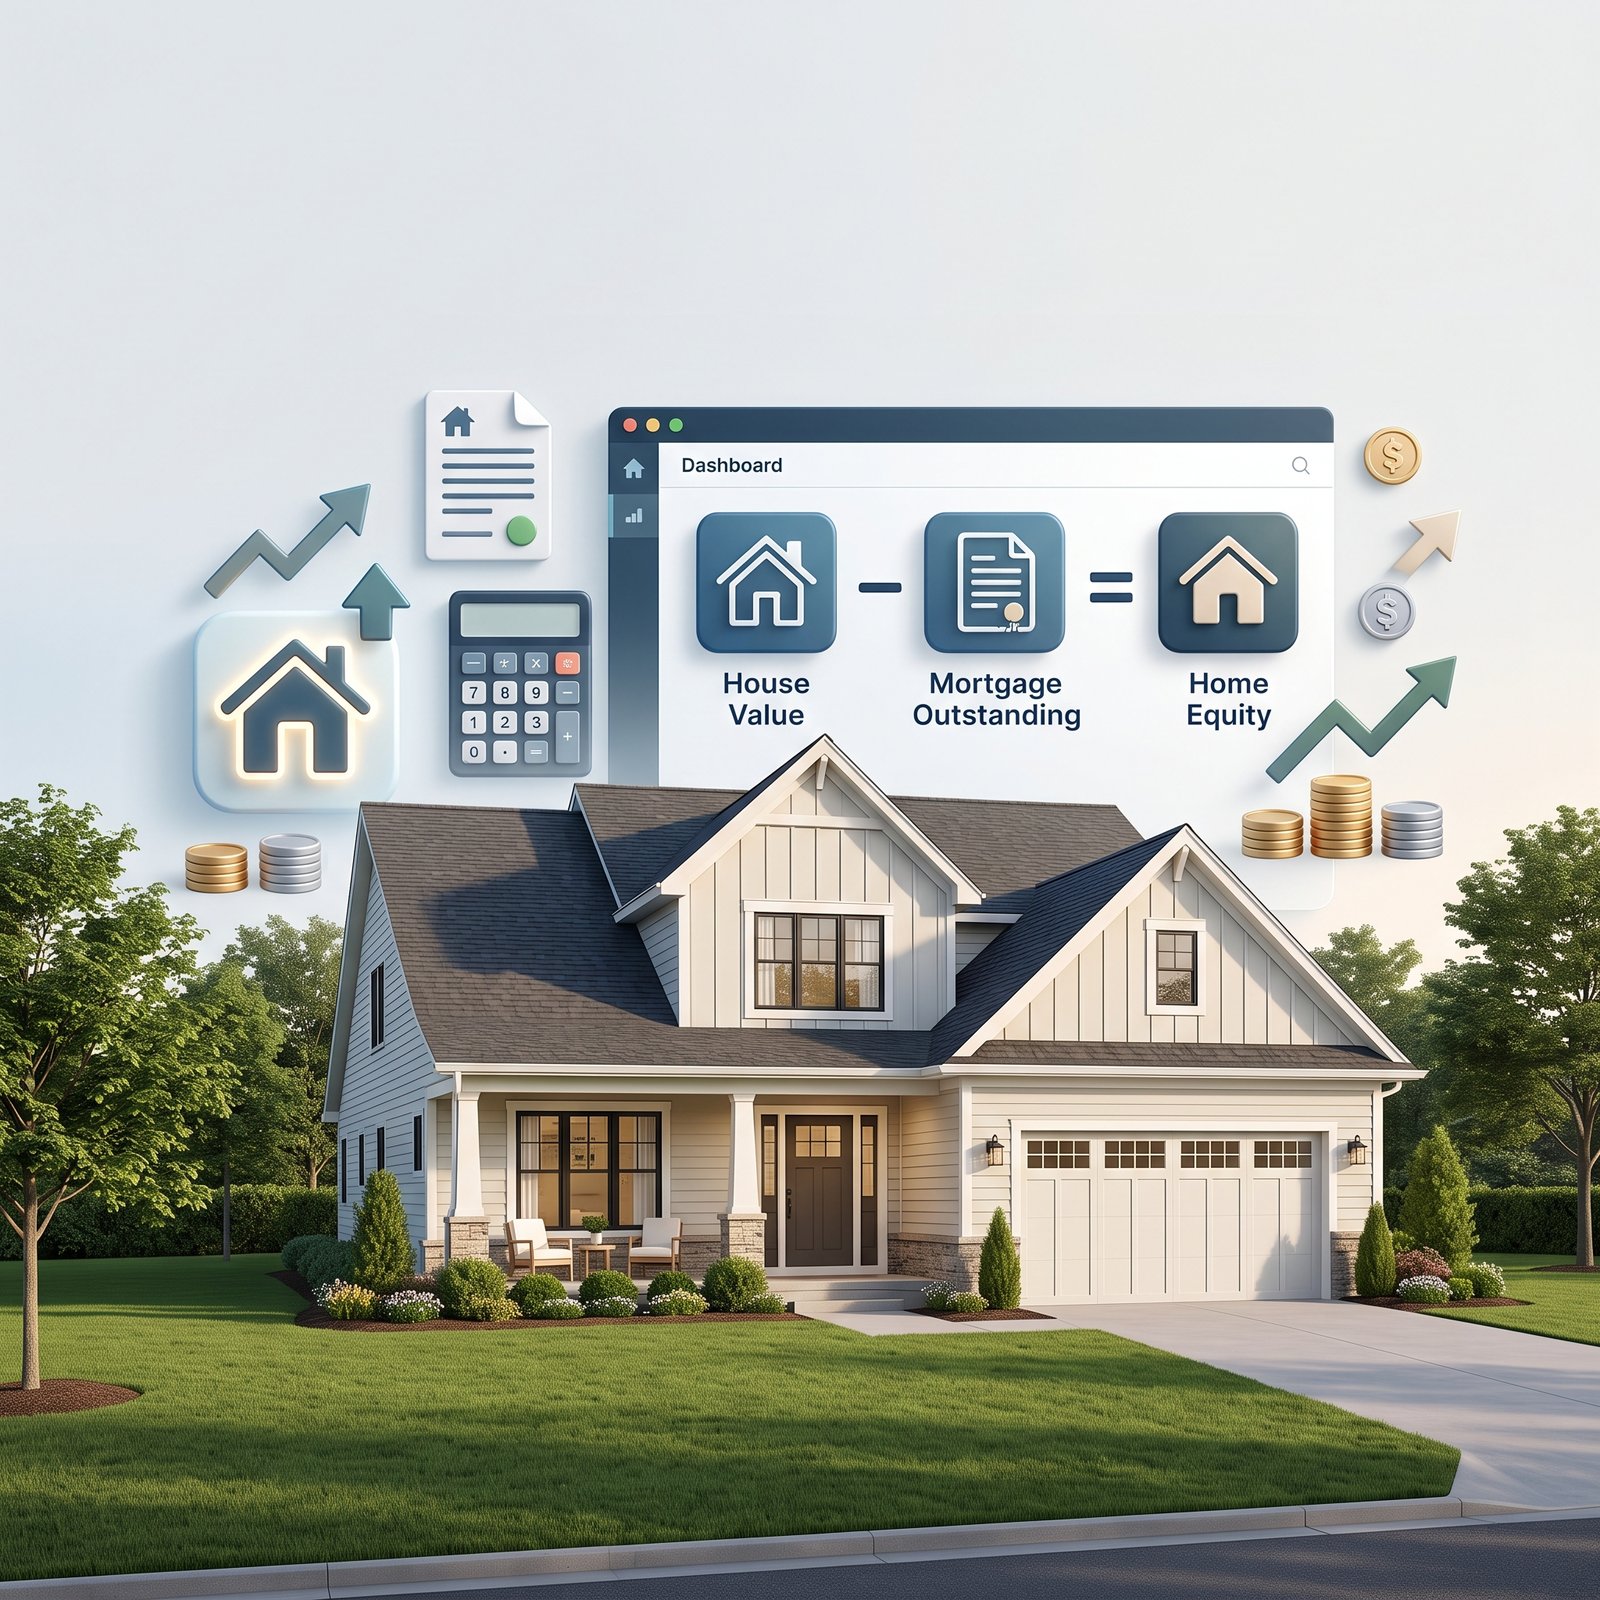
If you’re wondering does net worth include home, the short answer is yes. Your home is generally considered an asset and can be included when calculating your net worth. However, you typically should not simply add the full value of your home to your wealth without also accounting for any mortgage or other debt secured against the property.
The part of your home’s value that you actually own is called home equity. For example, if your home is worth $400,000 and you have $250,000 remaining on your mortgage, your home equity is $150,000.
Understanding the difference between home value, home equity, and mortgage debt is important when calculating your overall financial position.
Does Net Worth Include Your Home?
Yes, your home generally counts as an asset when calculating net worth.
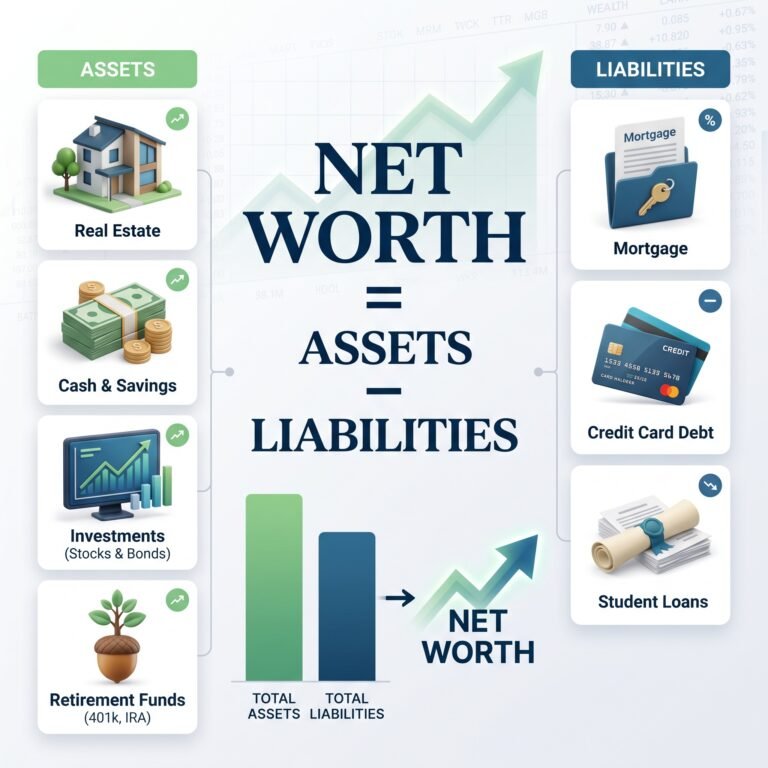
Net worth measures the difference between everything you own and everything you owe. The basic formula is:
Net Worth = Total Assets − Total Liabilities
Your assets can include:
- Your home
- Savings accounts
- Investments
- Retirement accounts
- Vehicles
- Business interests
- Other valuable personal assets
Your liabilities can include:
- Mortgage balances
- Credit card debt
- Auto loans
- Student loans
- Personal loans
- Other outstanding debts
Because your home has financial value, it belongs on the asset side of a net worth calculation. However, the mortgage associated with the property belongs on the liability side.
This means your net worth is affected by both the home’s current value and the amount you still owe on it.
A Simple Example
Suppose you own a home currently worth $400,000 and have an outstanding mortgage balance of $250,000.
Your calculation would be:
$400,000 home value − $250,000 mortgage = $150,000 home equity
That $150,000 represents the portion of the property’s value that contributes to your net worth after accounting for the mortgage.
Does Net Worth Include Your House?
If you’re asking does net worth include your house, the answer is also yes.
A house is a type of real estate asset, so its current estimated market value can be included among your total assets. But you also need to include any outstanding mortgage as a liability.
For example:
- House value: $500,000
- Mortgage balance: $300,000
- Home equity: $200,000
The $500,000 property is an asset, while the $300,000 mortgage is a liability.
When the two are considered together, the property contributes approximately $200,000 to your net worth.
It’s important to use the home’s current estimated value rather than automatically using the price you originally paid. Property values can rise or fall over time.
Does Net Worth Include Home Equity?
Yes. Home equity counts toward net worth.
Home equity is the portion of your home’s value that remains after subtracting the outstanding mortgage balance.
The basic formula is:
Home Equity = Current Home Value − Outstanding Mortgage Balance
For example:
Current home value = $500,000
Mortgage balance = $300,000
Home equity = $500,000 − $300,000 = $200,000
In this example, approximately $200,000 of the home’s value represents the owner’s equity, assuming there are no other property-related liabilities being considered.
As you pay down mortgage principal, your equity can generally increase. Your equity can also increase if your property appreciates in value.
However, home equity is not the same thing as cash in your bank account. You generally cannot spend your home equity directly without selling the property, borrowing against it, or otherwise accessing the equity.
Does Net Worth Include the Value of Your Home?
Yes, the value of your home can be included in your net worth calculation.
However, it is important to understand that net worth calculations account for both assets and liabilities.
Consider this example:
Home value: $400,000
Mortgage remaining: $250,000
Home equity: $150,000
If you have no other property-related debt, the home effectively contributes $150,000 to your net worth after the mortgage liability is accounted for.
This is why simply saying, “My house is worth $400,000, so I have $400,000 of wealth from my house,” can be misleading.
The amount you owe matters.
How to Calculate Your Home’s Contribution to Net Worth
You can estimate how much your home contributes to your net worth using a simple process.
1. Determine Your Home’s Current Value
Start with an estimate of the property’s current market value.
You might use a reputable property valuation tool, recent comparable sales, a real estate professional’s estimate, or a professional appraisal when greater accuracy is needed.
Avoid automatically using the original purchase price because the market value may have changed.
2. Find Your Outstanding Mortgage Balance
Check your latest mortgage statement or lender account to determine how much principal remains outstanding.
The original mortgage amount is not what you need. You need the current outstanding balance.
3. Subtract the Mortgage From the Home Value
Use this formula:
Home Equity = Home Value − Mortgage Balance
For example:
$500,000 − $300,000 = $200,000
4. Add Your Equity to Your Other Assets
Your home equity forms part of your overall financial position alongside your savings, investments, retirement accounts, vehicles, and other assets.
5. Subtract Your Other Liabilities
Finally, subtract your remaining debts and liabilities.
The overall formula remains:
Net Worth = Total Assets − Total Liabilities
Example of Net Worth With a Home
Imagine someone has the following financial position:
Assets
- Home: $500,000
- Savings: $30,000
- Investments: $70,000
- Retirement accounts: $100,000
- Vehicle: $25,000
Total assets = $725,000
Liabilities
- Mortgage: $300,000
- Car loan: $10,000
- Credit card debt: $5,000
Total liabilities = $315,000
Now calculate:
$725,000 − $315,000 = $410,000
The person’s estimated net worth is therefore $410,000.
Notice how the home is included as a $500,000 asset while the $300,000 mortgage is included separately as a liability.
Another way to understand the calculation is to look at the home’s equity:
$500,000 − $300,000 = $200,000 home equity
That $200,000 is the home’s net contribution before considering the person’s other assets and liabilities.
What Happens to Net Worth When Your Home’s Value Increases?
If your home’s market value increases while your mortgage balance stays the same, your home equity generally increases.
For example, suppose your home was worth $400,000 and your mortgage balance was $250,000.
Your equity would be:
$400,000 − $250,000 = $150,000
If the home’s estimated market value later rises to $450,000 and the mortgage remains $250,000:
$450,000 − $250,000 = $200,000
Your estimated home equity has increased by $50,000.
That can increase your net worth.
However, an increase in home value does not mean you suddenly have $50,000 in cash available to spend. The increase is primarily an increase in the estimated value of an asset.
Property values can also decline, which could reduce home equity and net worth.
What Happens to Net Worth When You Pay Off Your Mortgage?
Paying down mortgage principal generally increases your home equity.
Suppose your home is worth $500,000 and your mortgage balance falls from $300,000 to $280,000.
Your equity changes from:
$500,000 − $300,000 = $200,000
to:
$500,000 − $280,000 = $220,000
The $20,000 reduction in principal increases your equity by $20,000, assuming the home’s value remains unchanged.
Mortgage interest is different. Interest is generally a cost of borrowing rather than an increase in your ownership stake in the property.
This is why understanding the difference between principal and interest is useful when tracking changes in your net worth.
Should You Include Your Home in Your Net Worth?
For most homeowners, including their primary residence in a personal net worth calculation provides a more complete picture of their overall financial position.
However, you should distinguish between net worth and liquidity.
Your home can represent a substantial portion of your wealth, but it is not the same as money sitting in a checking or savings account.
For example, someone might have:
- $200,000 in home equity
- $20,000 in savings
- $50,000 in investments
Their net worth could be substantial, but only a portion of it may be readily accessible.
Net Worth vs. Liquid Net Worth
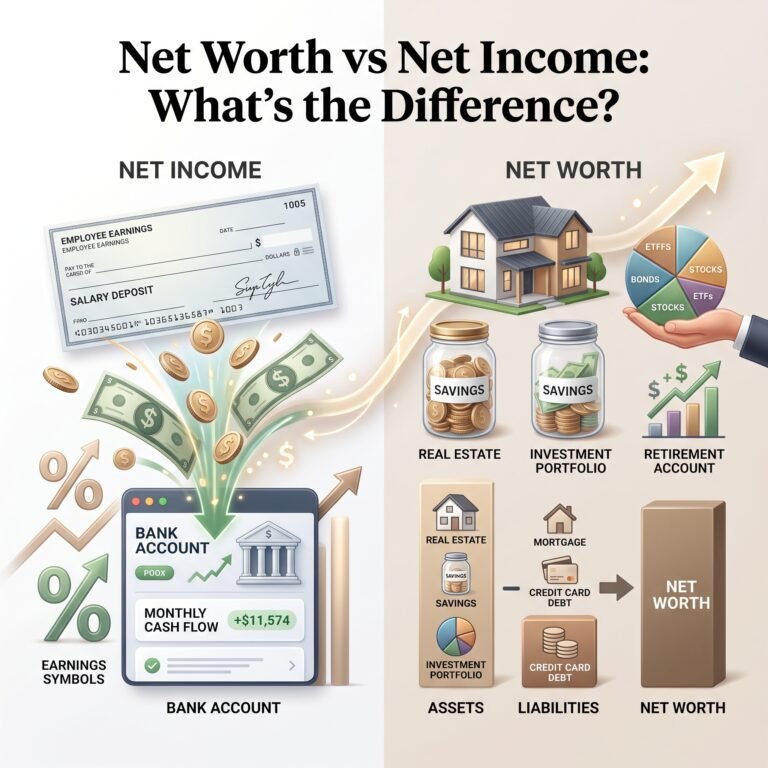
Net worth includes assets such as your home, retirement accounts, investments, vehicles, and other property, minus liabilities.
Liquid net worth focuses more heavily on assets that can be converted into cash relatively quickly, depending on how the calculation is defined.
This distinction matters because home equity may increase your net worth without providing immediate spending power.
Common Mistakes When Including a Home in Net Worth
Calculating net worth with real estate is straightforward, but several common mistakes can produce misleading results.
Using the Original Purchase Price
Your home’s current estimated market value may be different from what you originally paid.
Forgetting the Mortgage
Adding the full home value without accounting for the outstanding mortgage can overstate net worth.
Double-Counting the Mortgage
If you calculate home equity as home value minus mortgage and then also subtract the same mortgage again without including the full home asset, you can distort the calculation.
Choose one consistent approach.
Treating Home Equity as Cash
Home equity is an asset, but it is not equivalent to cash in a bank account.
Assuming Property Values Always Rise
Real estate markets can change. A home’s estimated value can increase or decrease depending on market conditions, location, property condition, and other factors.
Ignoring Other Property-Related Debt
If there are other debts secured against the property, they may also need to be considered when calculating your financial position.
Frequently Asked Questions
Does net worth include your home?
Yes. Your home is generally an asset and can be included in your net worth. Any outstanding mortgage is treated as a liability.
Does net worth include your house?
Yes. The current estimated value of your house can be included among your assets, while the remaining mortgage is included among your liabilities.
Does home equity count toward net worth?
Yes. Home equity represents the portion of the home’s value that you own after accounting for the outstanding mortgage and generally contributes to your net worth.
Do you include your mortgage when calculating net worth?
Yes. An outstanding mortgage is a liability and should be included when calculating net worth.
Should I use the purchase price or current value of my home?
For a current net worth estimate, the home’s current estimated market value is generally more useful than its original purchase price.
Is home equity considered liquid net worth?
Generally, no. Home equity can contribute to total net worth, but it is not the same as readily accessible cash or other highly liquid assets.
Does paying off a mortgage increase net worth?
Paying down mortgage principal generally increases your home equity and can increase your net worth, assuming other factors remain unchanged.
Conclusion
So, does net worth include home? Yes. A home is generally considered an asset and can be included when calculating your net worth. The key is to account for the mortgage and other relevant liabilities.
For example, if your home is worth $500,000 and you owe $300,000 on the mortgage, your home equity is approximately $200,000.
The broader calculation remains:
Net Worth = Total Assets − Total Liabilities
Including your home gives you a more complete view of your financial position, but remember that home equity is different from liquid cash. Your home’s value can change, and accessing its equity may require selling the property or using another financial arrangement.
For an accurate personal net worth calculation, keep your property value, mortgage balance, other assets, and liabilities updated regularly.