Does Liquid Net Worth Include a 401(k) or Retirement Accounts?
If you’re asking does liquid net worth include 401k, the answer depends on how you define and calculate liquid net worth. A 401(k) is generally an asset and is normally included when calculating total net worth. However, it may be excluded, discounted, or listed separately when calculating liquid net worth because retirement funds are not always as accessible as cash or taxable investments.
A 401(k) can have withdrawal restrictions, potential taxes, potential penalties, and employer-plan rules. These factors make it different from money in a checking account or a readily accessible brokerage account.
Understanding this distinction is important because someone can have a high total net worth while having considerably less wealth that is readily accessible. For a clearer financial picture, it can be useful to track both total net worth and liquid or accessible assets.
What Is Liquid Net Worth?
Liquid net worth generally focuses on assets that can reasonably be accessed or converted into cash relatively quickly.
Examples of assets that are commonly considered liquid include:
- Cash
- Checking accounts
- Savings accounts
- Money market accounts
- Certain brokerage investments
- Some short-term investments
The exact definition can vary depending on the person, financial institution, calculator, or purpose of the calculation. There is no single universally standardized formula for liquid net worth.
For example, money in a savings account is generally easy to access. A publicly traded stock in a brokerage account can generally be sold relatively quickly, although its market value can fluctuate.
A home is different. Even though a home can be extremely valuable, selling it can take time and involve transaction costs. The same applies to many other physical assets.
This is why being an asset does not automatically mean being a liquid asset.
What Is the Difference Between Net Worth and Liquid Net Worth?
The biggest difference is the type of assets being emphasized.
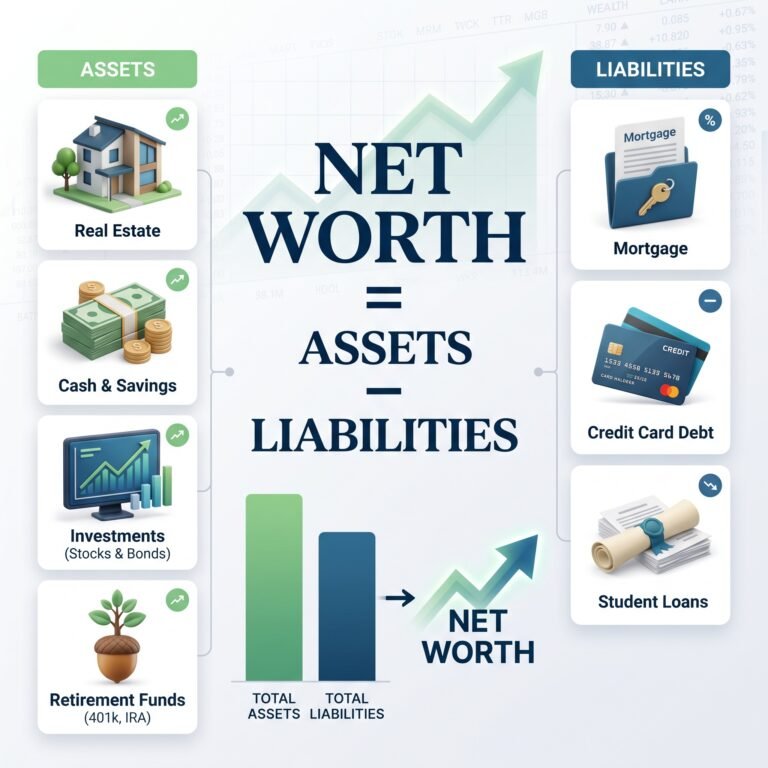
Total net worth measures your overall financial position:
Net Worth = Total Assets − Total Liabilities
It can include your home, retirement accounts, investments, cash, vehicles, and other assets, minus debts and other liabilities.
Liquid net worth, on the other hand, focuses more heavily on wealth that can reasonably be accessed or converted into cash without the same level of delay or difficulty.
| Asset or Liability | Total Net Worth | Liquid Net Worth |
|---|---|---|
| Cash | Included | Usually included |
| Savings | Included | Usually included |
| Stocks | Included | Often included |
| Brokerage investments | Included | Often included |
| Home | Included | Usually excluded |
| Home equity | Can increase net worth | Usually excluded |
| 401(k) | Generally included | Depends on definition/accessibility |
| IRA | Generally included | Depends on definition/accessibility |
| Mortgage | Liability | May be deducted depending on methodology |
| Credit card debt | Liability | May be deducted depending on methodology |
This distinction is important because liquid net worth is not simply another name for total net worth.
For example, someone could have $500,000 in total net worth but only $100,000 in relatively accessible financial assets. Much of the remaining wealth might be tied up in a home, retirement accounts, or other less-liquid assets.
Does Liquid Net Worth Include a 401(k)?
The answer to does liquid net worth include 401k depends on the methodology being used.
For Total Net Worth
A 401(k) is generally considered an asset and can be included in total net worth.
For example, if your 401(k) has a current balance of $100,000, that $100,000 can generally be listed among your assets when calculating overall net worth.
The basic calculation remains:
Net Worth = Total Assets − Total Liabilities
For Liquid Net Worth
A 401(k) may be excluded or treated differently when calculating liquid net worth.
Why? Because a retirement account may not provide the same immediate access as cash.
Factors that can affect its liquidity include:
- Withdrawal restrictions
- Potential taxes
- Potential penalties
- Employer-plan rules
- Your age and circumstances
- Investment market fluctuations
- Plan-specific restrictions
Some people may include retirement accounts in a broader calculation of liquid or accessible wealth, while others exclude them entirely.
Therefore, it is better to state your methodology rather than assume there is one universal answer.
The key question is:
Is the 401(k) an asset? Generally, yes.
Is the 401(k) liquid? That depends on the definition and how accessible the funds are.
Does Liquid Net Worth Include Retirement Accounts?
If you’re wondering does liquid net worth include retirement accounts, the answer is similar: retirement accounts are financial assets, but their treatment as liquid assets varies.
Common retirement accounts include:
- 401(k)
- Traditional IRA
- Roth IRA
- 403(b)
- Other employer-sponsored retirement accounts
These accounts have financial value and can contribute to total net worth. However, they may not be treated the same way as cash when calculating liquid wealth.
This is an important distinction between ownership and accessibility.
A person may own $150,000 in a retirement account, but that does not necessarily mean they have $150,000 available to spend today.
Retirement accounts are generally designed for long-term retirement savings. Their rules can make them less accessible than ordinary bank accounts or taxable brokerage accounts.
For that reason, a useful financial tracking system can show retirement assets separately from readily accessible assets.
Are 401(k) Accounts Considered Liquid Assets?
A 401(k) has financial value, but whether it should be classified as a liquid asset depends on the definition being used.
Cash is highly liquid because you can generally use it immediately.
A brokerage account is often considered relatively liquid because investments such as stocks and ETFs can generally be sold through the account, although prices can change.
A 401(k) can be less accessible because it is a retirement plan with its own rules.
For this reason, many people distinguish between:
Retirement wealth and readily accessible wealth.
This distinction becomes especially useful when evaluating whether you have enough accessible money to handle an unexpected expense.
A person with $200,000 in retirement savings and $5,000 in savings may have substantial long-term wealth but relatively limited readily accessible funds.
Does an IRA Count Toward Liquid Net Worth?
Traditional and Roth IRAs are generally financial assets and can be included in total net worth.
Whether they belong in liquid net worth is less straightforward.
Traditional IRA
A traditional IRA is a retirement account that can hold investments. Its balance represents an asset, but withdrawals may have tax implications and other considerations.
Roth IRA
A Roth IRA is also a retirement asset. Its tax treatment differs from a traditional IRA, but it should not automatically be treated as equivalent to cash simply because it may have certain withdrawal features.
For liquid-net-worth purposes, the important issue is accessibility and the methodology being used.
Some calculations may include retirement accounts at their current value. Others may exclude them or track them separately.
The best approach is to clearly define your calculation and use the same approach consistently.
Do Brokerage Accounts Count Toward Liquid Net Worth?
Taxable brokerage accounts are often treated as more liquid than retirement accounts.
A brokerage account may contain:
- Stocks
- ETFs
- Bonds
- Mutual funds
- Cash
- Other investments
These investments can generally be sold, although selling an investment does not guarantee that you will receive the amount you originally invested.
For example, if you have $75,000 in a brokerage account, the account may be considered part of your liquid assets under many approaches.
However, there is an important difference between liquid and risk-free.
An investment can be relatively easy to sell while still losing value because of market movements.
Therefore, a $75,000 brokerage account is not necessarily equivalent to $75,000 sitting in an insured savings account.
Does Home Equity Count Toward Liquid Net Worth?
Home equity can contribute to total net worth, but it is generally treated differently from liquid assets.
For example:
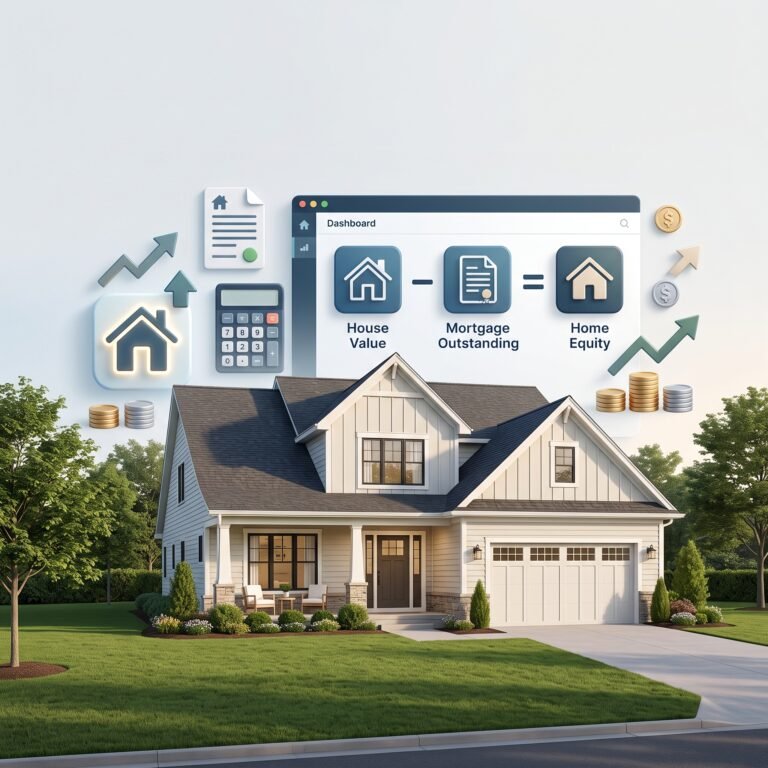
Home value = $500,000
Mortgage balance = $300,000
Home equity = $200,000
The $200,000 of equity can contribute to your total net worth.
However, home equity is generally not considered liquid because accessing it may require selling the property, refinancing, or using another form of borrowing.
Selling a home can involve:
- Time
- Transaction costs
- Financing considerations
- Market conditions
- Moving expenses
This makes home equity fundamentally different from cash.
For more information about how a home fits into overall net worth, see Does Net Worth Include Your Home?
Does Cash and Savings Count Toward Liquid Net Worth?
Cash and readily accessible savings are among the clearest examples of liquid assets.
These may include:
- Checking accounts
- Savings accounts
- Cash
- Money market accounts
- Certain short-term investments
Their main advantage is accessibility.
If you have $20,000 in a savings account, you can generally access that money much more easily than $20,000 of home equity.
Likewise, retirement accounts can have additional rules that make them less straightforward to access.
This is why people often track cash and savings separately when evaluating their financial flexibility.
Example of Liquid Net Worth With a 401(k)
Consider this fictional example.
A person has:
- Checking and savings: $30,000
- Brokerage account: $70,000
- 401(k): $150,000
- Home equity: $200,000
- Vehicle: $20,000
Their liabilities include:
- Mortgage: $250,000
- Auto loan: $10,000
For total net worth, we can calculate the assets first:
$30,000 + $70,000 + $150,000 + $200,000 + $20,000 = $470,000
Then subtract liabilities:
$470,000 − $260,000 = $210,000
So the person’s estimated total net worth is $210,000.
Now consider liquid net worth.
If the methodology includes only cash and brokerage investments, the liquid assets would be:
$30,000 + $70,000 = $100,000
Under that methodology, the 401(k), home equity, and vehicle would not be counted as liquid assets.
However, another methodology might treat some or all retirement assets differently.
This example demonstrates why the definition being used should always be stated clearly.
Total Net Worth vs Liquid Net Worth Example
Here is another simplified example:
| Asset | Value | Total Net Worth | Liquid Net Worth |
|---|---|---|---|
| Cash | $20,000 | Included | Included |
| Brokerage | $80,000 | Included | Included |
| 401(k) | $120,000 | Included | Depends |
| Home equity | $200,000 | Included | Usually excluded |
| Vehicle | $25,000 | Included | Usually excluded |
The person’s total assets shown here equal:
$20,000 + $80,000 + $120,000 + $200,000 + $25,000 = $445,000
For total net worth, all of these assets may be considered, followed by subtracting liabilities.
For liquid net worth, the calculation may focus primarily on the $20,000 cash and $80,000 brokerage balance. The 401(k) could either be excluded or treated separately depending on the chosen methodology.
This is why two people can calculate “liquid net worth” differently and both be using reasonable approaches—as long as they clearly define what they are including.
Why Would Someone Calculate Liquid Net Worth?
Liquid net worth can provide information that total net worth does not.
It can help you understand:
Emergency Financial Capacity
How much wealth could potentially be accessed without relying heavily on selling property or accessing retirement funds?
Financial Flexibility
A person with more accessible assets may have greater flexibility when facing an unexpected expense.
Major Purchases
Liquid assets can be useful when evaluating the financial impact of a major purchase.
Financial Planning
Tracking accessible assets separately from retirement and real estate wealth can provide a clearer picture of different parts of your financial position.
Overall Financial Health
Total net worth tells you how much wealth you have overall, while liquid net worth can provide additional insight into how much of that wealth is relatively accessible.
Neither measurement tells the complete story on its own.
How to Calculate Liquid Net Worth
Because liquid net worth does not have one universally standardized definition, start by deciding what your calculation will include.
Step 1: List Your Liquid Assets
Identify assets that can reasonably be accessed or converted into cash relatively quickly.
These may include:
- Cash
- Checking
- Savings
- Money market accounts
- Brokerage investments
Step 2: Decide How to Treat Retirement Accounts
Determine whether you will:
- Exclude retirement accounts
- Include them at their current value
- Include only certain accounts
- Track them separately
The most important point is consistency.
Step 3: Identify Less-Liquid Assets
These may include:
- Primary residence
- Home equity
- Vehicles
- Collectibles
- Certain private investments
- Other difficult-to-sell property
These assets can still contribute to total net worth.
Step 4: Account for Relevant Liabilities
Depending on the purpose of your calculation, determine which liabilities should be deducted.
For example, some approaches may subtract all liabilities, while others may focus on liabilities associated with liquid assets.
Step 5: Calculate the Result
A simple framework is:
Liquid Net Worth = Liquid Assets − Relevant Liabilities
Because methodologies vary, clearly state what you included and excluded.
Should You Include Your 401(k) in Your Net Worth?
For total net worth, generally yes.
A 401(k) is a financial asset and can be included alongside your other assets.
For liquid net worth, the answer depends on your methodology and how accessible you consider the account.
A practical approach is to track two separate numbers:
Total Net Worth
and
Accessible or Liquid Assets
This gives you a better understanding of both your overall wealth and the portion that may be more readily available.
For example, someone might have a $500,000 total net worth but only $100,000 in accessible assets. That distinction can be important for financial planning.
Common Mistakes When Calculating Liquid Net Worth
Treating Every Asset as Liquid
A home, vehicle, or retirement account can have significant value without being immediately accessible.
Automatically Treating a 401(k) Like Cash
A 401(k) is valuable, but retirement-plan rules can make it different from money in a checking or savings account.
Including Home Equity Without Considering Liquidity
Home equity can increase total net worth but is generally not readily spendable.
Ignoring Liabilities
Assets alone do not determine net worth. Debts and other liabilities matter.
Using Outdated Values
Investment and account balances change. Use reasonably current figures when calculating your financial position.
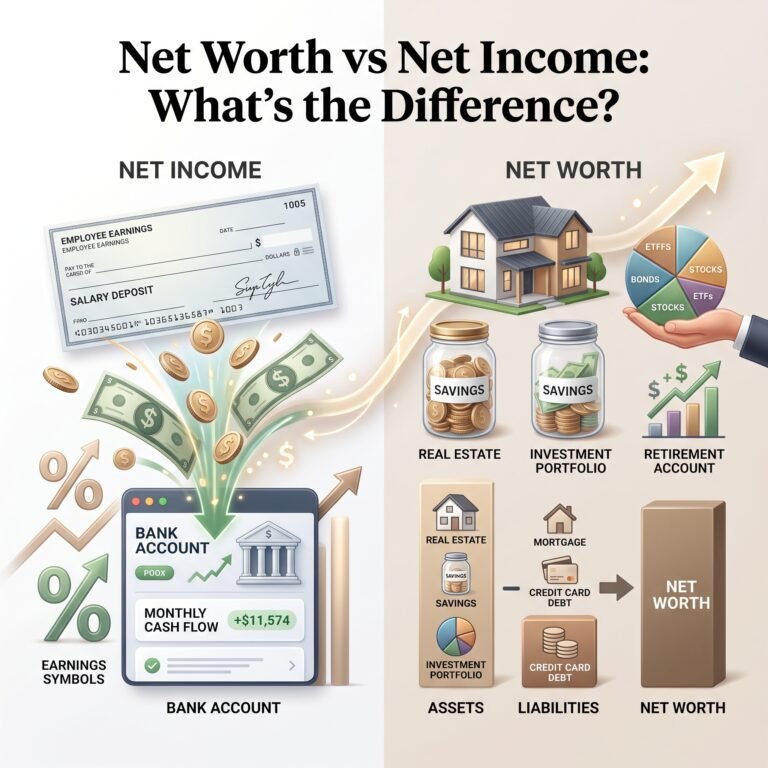
Confusing Income With Net Worth
Income is the money you earn. Net worth is the value of your assets minus liabilities.
Assuming Every Calculator Uses the Same Formula
Different financial tools can define liquid net worth differently. Always check what the calculation includes.
Frequently Asked Questions
Does liquid net worth include a 401(k)?
It depends on the methodology. A 401(k) is generally included in total net worth, but it may be excluded or separately identified when calculating liquid net worth because retirement funds may have accessibility restrictions.
Is a 401(k) considered liquid?
A 401(k) is a financial asset, but it is not always considered a liquid asset. Its treatment depends on accessibility and the definition of liquid net worth being used.
Does liquid net worth include retirement accounts?
There is no single universal rule. Some calculations include retirement accounts, while others exclude them or track them separately because retirement funds may not be immediately accessible.
Is a Roth IRA considered liquid?
A Roth IRA is a financial asset, but whether it is considered liquid depends on the methodology. Its treatment should not automatically be equated with cash or a regular savings account.
Does home equity count toward liquid net worth?
Home equity generally contributes to total net worth but is usually excluded from liquid net worth because accessing it can require selling or borrowing against the property.
What assets are considered liquid?
Cash, checking accounts, savings accounts, money market accounts, and certain readily tradable investments are commonly considered liquid or relatively liquid assets.
What is the difference between net worth and liquid net worth?
Total net worth measures assets minus liabilities across your overall financial position. Liquid net worth focuses more specifically on wealth that can reasonably be accessed or converted to cash relatively quickly.
Should I include my 401(k) in my net worth?
Generally, yes. A 401(k) is normally considered an asset and can be included in total net worth. For liquid net worth, you should decide how retirement assets will be treated and apply that methodology consistently.
Conclusion
So, does liquid net worth include 401k? There is no single answer that applies to every liquid-net-worth calculation. A 401(k) is generally an asset and should normally be included when calculating total net worth. However, it may be excluded, discounted, or tracked separately when calculating liquid net worth because retirement accounts can have withdrawal restrictions, taxes, penalties, and other accessibility considerations.
The same principle applies to other retirement accounts. Does liquid net worth include retirement accounts? It depends on the definition and methodology you choose.
The most useful approach is often to track both total net worth and accessible or liquid assets. Total net worth shows your broader financial position, while liquid net worth can help you understand how much of your wealth may be relatively accessible.
The key distinction is simple:
An asset can have substantial value without being highly liquid.
Keeping these two measurements separate can give you a much clearer picture of both your long-term wealth and your financial flexibility.